Why is the market valuing Decibel at less than 2× our projected 2027 EBITDA?
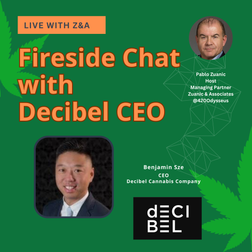
Why is the market valuing Decibel at less than 2× our projected 2027 EBITDA? We sat down with Benjamin Sze, CEO of Decibel Cannabis Company, following the company's latest quarterly results. In this 11-minute conversation, we discuss: Q2 revenue and EBITDA Domestic growth and market-share gains International expansion • EU-GMP processing 50 cultivator customers and 16 overseas distributors Free cash flow generation Raised 2026 guidance The company's strategic value in a consolidating industry Our latest report rates Decibel Overweight. Our CY27 estimates imply 0.5× sales and 1.8× EBITDA. And while Zuanic & Associates does not publish price targets, our analysis shows that applying a 10× EBITDA multiple to our projected 2027 EBITDA would imply greater than 5× upside by December 2026. Read the full research report and watch the CEO interview for the complete thesis, assumptions and risks. #Decibel #DecibelCannabis #DB #DBCCF #TSXV #OTCQB #Stocks #Investing #EquityResearch #SmallCapStocks #CanadianStocks #GrowthStocks #MarketAnalysis